
UAE VAT on Employee Expenses: 6 Categories You Can Recover (Decision 17 of 2026)
Every business owner in the Emirates pays for something that helps their team work: a staff bus, a phone plan, a parking slot, a room for a new joiner. Until recently, many companies were unsure whether the VAT on those costs could be claimed back. UAE VAT on employee expenses is now much clearer, because the Federal Tax Authority (FTA) has published a defined list of cases and conditions.
The new rules come from FTA Decision No. 17 of 2026, which was issued in September and took effect on 1 October 2026. It confirms six categories where a VAT-registered business may achieve input VAT recovery UAE when it provides goods or services to employees free of charge under a contract or a documented policy. It is good news, but it comes with strict conditions.
This guide explains each category in plain language, the conditions that apply, the records you need and the mistakes that can cost you the claim. It is written for owners, finance managers and HR teams across Dubai, Abu Dhabi, Sharjah and the other emirates who want to apply the rules correctly from the start.
At VAT Accounting UAE, we help businesses review their staff benefits, update policies and claim only what the law allows. This article is general information rather than legal advice, so please confirm your specific position with a qualified adviser.
What FTA Decision No. 17 of 2026 Changes for UAE Businesses
Before this decision, the general rule was that input tax is recoverable only when costs are incurred for making taxable supplies, and many employee benefits sat in a grey area. The FTA Decision No. 17 of 2026 removes much of that uncertainty by listing six specific cases where recovery is allowed, provided every condition for that case is met.
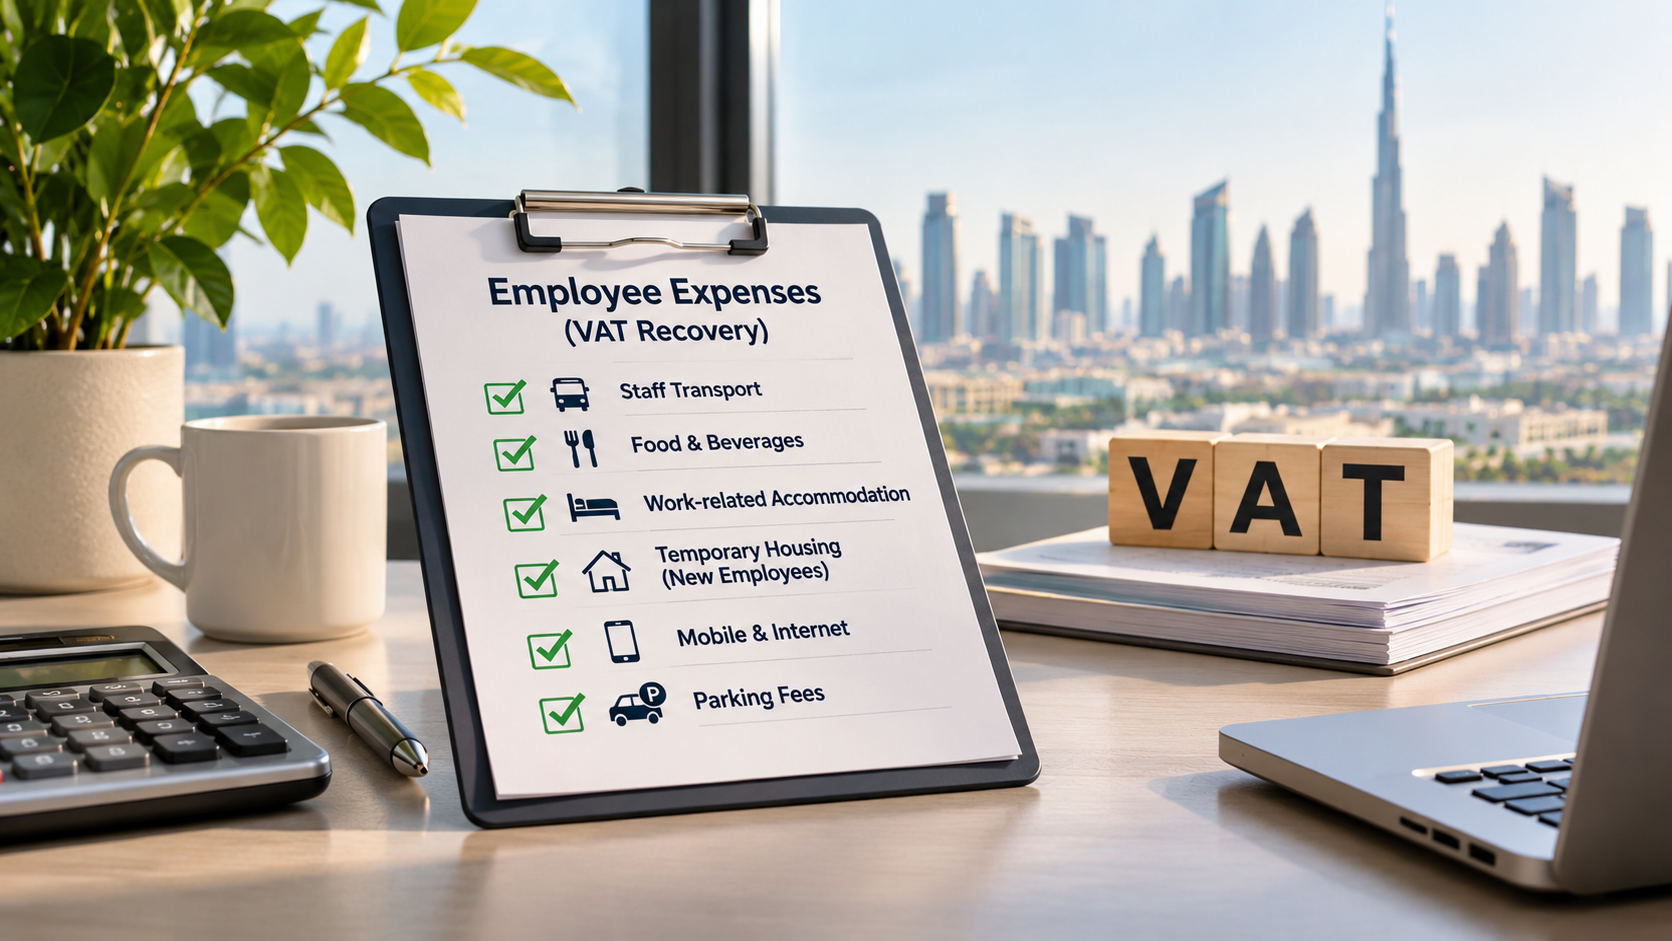
The six categories are transport, food and beverages, work-related accommodation, temporary housing for new employees, mobile phones and internet, and parking fees. If a benefit is not on the list, the wider VAT rules still apply, and recovery is not automatic. The decision does not give a general right to reclaim VAT on every staff perk.
A crucial point is that you recover only the VAT portion, not the full cost. If an eligible service costs AED 105 including AED 5 VAT, the recoverable input tax UAE amount is the AED 5 tax component alone, and only when all requirements are satisfied. The rest remains an ordinary business cost.
The change matters for any company with a team, from a small trading firm to a large employer. Our VAT services team reviews these cases with clients so that staff benefits are correctly reflected in every return.
Conditions for Input VAT Recovery on Employee Benefits UAE
The conditions for input VAT recovery on employee benefits UAE start with a basic requirement: the benefit must be provided free of charge under a contractual obligation or a documented internal policy. A casual verbal arrangement is not enough, and a policy that only exists in someone’s head will not satisfy the FTA.
The second requirement is business purpose. The expense must be directly connected to the company’s activities and operational needs, not simply a personal benefit that happens to be paid by the employer. Each category then has its own detailed tests, and every one of them must be met together.
The third requirement is that the employee must not be able to take cash instead. Where staff can choose a cash allowance in place of the transport, meal or housing provided, recovery is generally blocked. This single point catches many businesses, because flexible allowance structures are common in the UAE.
The fourth requirement is proof. You must hold a valid tax invoice or receipt showing the supplier, date, amount and VAT charged. Good VAT accounting services help you capture these documents at the time of the expense, which is far easier than searching for them during an FTA review.
VAT on Employee Transport and Food and Beverages in the UAE
VAT on employee transport UAE can be recovered where the service is used exclusively for journeys between home and workplace, trips to client premises or other travel directly related to duties. The transport must not serve a personal purpose, and employees must not have the choice of taking a cash transport allowance instead. Companies with fleets of staff buses, such as logistics companies, should review their arrangements carefully.
VAT on food and beverages for employees in the UAE is more limited. Recovery applies where employees work or live in remote or isolated locations without suitable facilities to prepare food and without nearby restaurants where they can easily obtain meals. The meals must be tied to the work or residence period the job requires.
The same cash rule applies here as well. If workers can receive a meal allowance in place of the meals provided, the VAT is not recoverable. The decision also does not cover ordinary daily lunches for office staff, even when the employer pays for them.
In practice, this means a catered canteen at a remote labour site may qualify, while a weekly team lunch at a city office usually will not. Businesses should classify each meal arrangement honestly and keep the supporting facts on file.
VAT on Staff Accommodation, Staff Housing and Temporary Housing
Many employers ask, “can I claim VAT on employee accommodation in UAE?” The answer is yes, but only in defined situations. VAT on staff accommodation UAE is recoverable when the housing is provided because of operational requirements, is not part of the employee’s normal remuneration, and the nature of the job requires living near the workplace, project site or client premises.
The accommodation must be designated for the employee concerned and must not include family members or personal uses. It must also be proportionate to the job and basic living needs, without recreational or luxury extras. A basic room near a remote site is treated very differently from a premium apartment offered as a perk.
This is particularly relevant for construction companies and other project-based businesses that house crews near work sites. VAT on staff housing UAE that forms part of a salary package, or where staff can take a housing allowance instead, does not qualify. A cash housing allowance simply remains outside the recovery route.
The decision also covers VAT on temporary housing for new employees UAE. Companies may recover input VAT on temporary accommodation for newly recruited staff for a period of up to 30 days, provided it is appropriate to the job and basic needs. Anything beyond that period needs separate analysis.
VAT on Mobile Phones, Internet and Parking Fees
Many readers ask whether companies can recover VAT on staff mobile bills UAE. Under the decision, VAT on mobile phones, calls, data packages and home internet through a router can be recovered where these are necessary for the employee’s duties, including remote work and job-related communication outside normal hours.
The services must be used mainly for business, although limited and incidental personal use is acceptable. The employer must have a documented internal policy that sets out permitted usage and the consequences of misuse. It must also apply reasonable monitoring and keep records to justify the claim.
VAT on parking fees UAE follows a similar logic. Input VAT is recoverable where the company bears the cost only for business purposes, such as external visits and meetings. The employer needs a written policy that explains when parking will be reimbursed and how claims are approved.
Receipts matter a great deal for parking, because they should show the date and time, the amount charged and the VAT paid. Strong bookkeeping services make it easy to match each receipt to an approved claim, which keeps small amounts from turning into audit problems.
Is VAT Recoverable on Cash Allowance in the UAE?
A frequent search is “is VAT recoverable on cash allowance UAE”. In general, no. When an employer pays a cash housing, transport or meal allowance, the employee chooses how to spend it, and the arrangement does not fit the free-of-charge supply the decision describes.
The more important point is the option. Even if you also provide a benefit in kind, giving employees the option to take cash instead can block the VAT claim for that category. This is why some companies are reviewing their employment contracts and allowance structures.
There may be good commercial reasons to keep allowances, and this is a business decision rather than a tax rule. What matters is understanding the VAT result, so that you do not claim input tax that the FTA may later reject along with penalties.
Before you change a benefit structure, compare the VAT saving with the effect on staff satisfaction and retention. Our VAT return filing specialists can help you test the numbers and make sure the correct figures go into each return.
Documented Internal Policy for VAT Recovery UAE
A documented internal policy for VAT recovery UAE is now a practical necessity. A short written policy should list which benefits the company provides, who is eligible, why the benefit is needed for the business, and how claims are approved. It should be signed off by management and shared with the relevant teams.
The policy should also explain that cash alternatives are not offered for the covered benefits, define reasonable personal use for items like phones, and describe the monitoring process. A policy that exists on paper but is never followed is a risk, so consistency matters.
Keep the evidence together. That means tax invoices, receipts, approvals, housing assignments and any monitoring reports, stored for the period the law requires. If the FTA asks questions, well-organised documents can settle the matter quickly, and a periodic audit and assurance review can test whether your records are ready.
If you have already deducted VAT on these items in earlier periods, review them against the new conditions. Where claims were missed, a proper VAT refund review may help recover what you are entitled to, and where errors were made, early correction is usually better than waiting.
How VAT Accounting UAE Helps with Employee Expense VAT
Our team starts with a simple health check. We list every benefit your company gives employees, compare it with the six categories and tell you which ones can support a claim. You receive a clear summary in plain language, without technical jargon.
Next, we help you draft or improve your internal policy, update contract wording where needed and set up a record-keeping routine. If your business is newly growing, our VAT registration support ensures you are properly registered before you start claiming input tax.
We also offer wider guidance through our tax consultancy service, because employee benefit decisions can affect Corporate Tax and payroll as well. Our remote service model lets you work with us from anywhere in the UAE.
Speak to VAT Accounting UAE today to review your staff expenses before your next VAT return. Book a free consultation and let us confirm what you can claim.
Final Word
Employee benefits can support your team and reduce your tax cost, but only when they are structured and documented correctly. By understanding UAE VAT on employee expenses, applying FTA Decision No. 17 of 2026 carefully and managing input VAT recovery UAE with good records, your business can claim confidently and avoid disputes.
Frequently Asked Questions (FAQs)
1. Can I claim VAT on employee accommodation in the UAE?
Yes, in limited cases. The housing must be needed for operational reasons, required by the job, designated for the employee and not part of normal pay. A cash housing allowance does not qualify.
2. Can companies recover VAT on staff mobile bills UAE?
Yes, when phones and the internet are necessary for work duties and used mainly for business. You need a documented policy, reasonable monitoring and proper records.
3. What about VAT on temporary housing for new employees UAE?
Input VAT on temporary accommodation for newly recruited staff can be recovered for up to 30 days, as long as the accommodation suits the job and basic needs.
4. Is VAT recoverable on cash allowance UAE?
Generally no. Cash allowances and arrangements that let employees choose cash instead of the benefit are not covered by the recovery route.
- What are the conditions for input VAT recovery on employee benefits UAE?
The benefit must be free to the employee under a contract or documented policy, linked to business needs, free of any cash option, and supported by valid tax invoices and records.
6. Do I need a documented internal policy for VAT recovery UAE?
Yes. Several categories, including mobile services and parking, require a written policy, approval procedures and monitoring, so a documented policy is the safest approach for all benefits.